 |
Consolidation, inflation, product availability and the rapid expansion of data center construction are not separate issues. They are overlapping and reshaping where companies invest, how they compete and how distributors and manufacturers serve their customers.
Business remains active, but it is uneven. Some markets are benefiting from historic levels of investment, while others are contending with slower construction activity, higher borrowing costs, delayed projects and customers who remain cautious about what comes next.
Having spent 20 years on the manufacturing side of the business and now working on the distribution side, I have seen how these pressures affect each part of the supply chain. I have seen why neither side can navigate them successfully without the other.
 |
| Kitchens |
CONSOLIDATION AND COMPETITION
Consolidation continues throughout the industry, with acquisitions occurring among distributors, customers and manufacturers. Consolidation can provide greater scale, purchasing power, technology and access to capital, but it can also disrupt long-standing relationships and change product priorities.
Regardless of company size, local knowledge, inventory availability, reliable service and the ability to solve customer problems remain important competitive advantages.
That becomes particularly important as companies expand into markets where they have not historically operated.
Competition is healthy. It forces all of us to improve our service, sharpen our pricing, invest in inventory, and demonstrate our value. However, entering a market is much easier than truly becoming part of that market. Opening a building and stocking inventory does not automatically create customer relationships.
Long-term success still requires local knowledge, reliable service, talented employees, strong supplier partnerships, and a willingness to support customers after the largest projects are completed or construction activity moves elsewhere.
The real test will be whether companies entering these markets are making a long-term commitment or simply chasing the current opportunity. Customers, employees, and manufacturers will remember which companies continue investing in the market when conditions become more challenging.
Inflation is another challenge affecting nearly every level of the supply chain. Manufacturers are facing higher costs related to labor, raw materials, energy, transportation, tariffs and regulatory requirements.
Those costs eventually move through distribution and reach the end user.
The difficult position for distributors is that we are often the ones explaining those increases to customers. When price adjustments occur repeatedly, customers do not always see the cost pressures behind them. They simply see another increase.
That makes communication between manufacturers and distributors more important than ever. Distributors need clear information, reasonable notice and an explanation they can take to their customers. Manufacturers also need distributors to communicate what is happening in the marketplace rather than simply resisting every increase.
This environment also requires discipline. Inventory must be managed strategically without falling into panic buying. Quotations need clear expiration and review dates, sales teams need to understand replacement-cost pricing, and customers should hear about potential changes as early as possible. Protecting margin is important, but protecting trust is equally important.
THE DATA CENTER EFFECT
Data center construction is also reshaping our industry. Investment in artificial intelligence, cloud computing, power generation and the infrastructure required to support these facilities is creating tremendous opportunity. It also puts enormous pressure on the availability of certain products and materials.
Large data center projects consume significant quantities of electrical gear, cable, conduit supports, struts, fasteners, safety products, material-handling equipment and tools. When manufacturers prioritize the largest projects or products become allocated, the effects are not limited to the data center market.
Contractors working on hospitals, schools, manufacturing plants, public infrastructure and everyday commercial projects can also experience longer lead times and reduced availability.
This creates a difficult balancing act for distributors. We want to support these major projects, but we cannot forget the customers and markets that built our businesses.
Committing too much inventory to one project, one customer, or one rapidly growing market can create risk, especially when construction schedules change or projects are delayed.
Data centers are an important part of our industry’s future, but they are not the entire industry.
The opportunity surrounding data centers is also driving distributors to expand into new geographic markets. Companies are opening branches, adding distribution centers, hiring salespeople, and entering markets where they previously had little or no presence. In some areas, established distributors are seeing the number of competitors double or even triple in a short period .
EXECUTION MATTERS
Optimism cannot replace execution.
I remain optimistic about our industry and what STAFDA distributors and manufacturers contribut every day to construction, infrastructure, manufacturing, utilities and transportation. But that optimism depends on continued communication, stronger partnerships and a clear-eyed understanding of the pressures affecting both sides of the supply chain.
Neither manufacturers nor distributors can succeed alone. If we remain focused on the value we provide together, our industry will be prepared to capitalize on the opportunities ahead while navigating the challenges that come with them.
DATE AND TIME
The State of the Industry and STAFDA will be discussed during the General Session, Monday, November 16, 9:45 – 11 a.m.
This article originally appeared in the October/November 2026 issue of Contractor Supply magazine. Copyright, 2026 Direct Business Media.

CONTRACTOR SUPPLY MAGAZINE
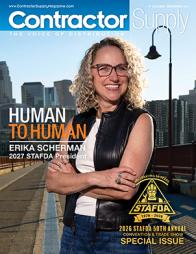
The October/November 2026 issue of Contractor Supply magazine is here!
In our cover story, Human to Human, MC Tool & Safety Sales competes with larger distributors by putting relationships, service and customer knowledge first.
Also in this issue are Industry Updates.
The digital edition, sponsored by BECK AMERICA Inc., is fully searchable and contains live links to every advertiser and new product listing. Click away!
| Read the Articles Read the Digital Edition |